
(+612) 2531 5600
info@la-studioweb.com
Get direction
Google map

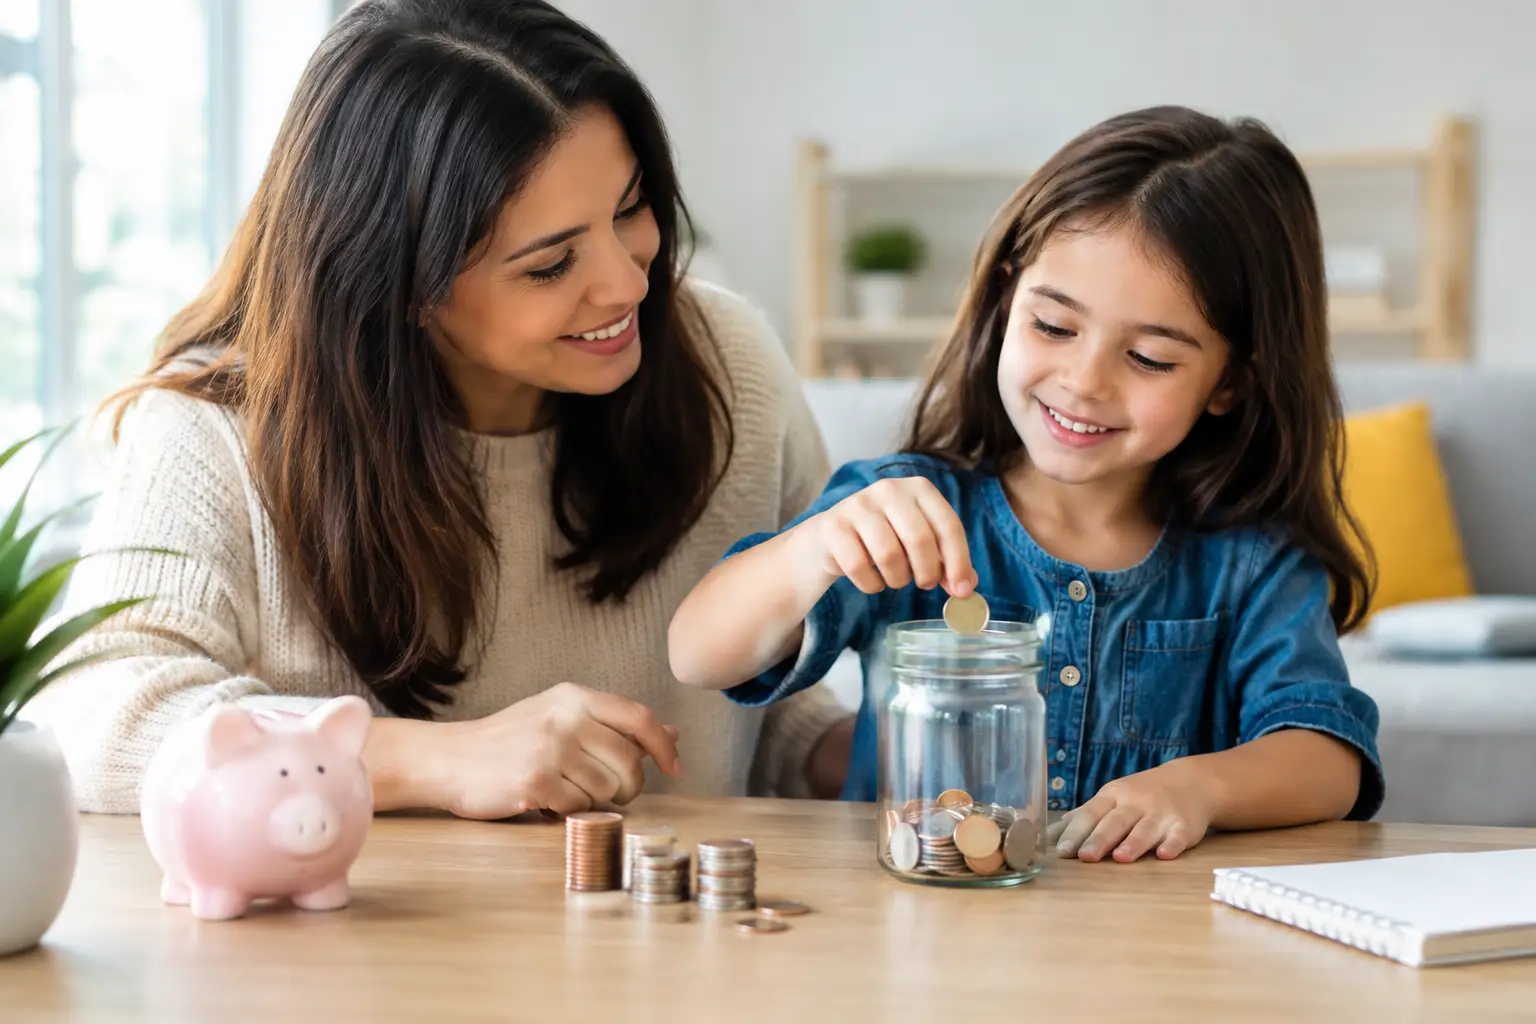
A child who can tap a screen to buy a game upgrade before they can count change is not irresponsible. They are growing up in a system designed to make spending feel invisible. That is why a guide to teaching money skills has to go beyond saving coins in a jar. Children need to see money, handle it, wait for it, make choices with it, and learn that online purchases are real purchases.
The good news is that money habits do not require a finance degree or a perfect family budget. They grow through ordinary moments: a grocery store request, a birthday check, a subscription renewal, or a conversation about why the newest device is not automatically the right choice. These moments can become the instruction manual you never got for raising a capable, grounded child.
Screens have changed the way children experience money. A physical dollar bill has limits. A digital wallet, saved credit card, in-game currency, and one-click checkout can make spending feel like play. Children may understand that something costs money without fully understanding that money is limited, earned, and connected to family priorities.
This is not an argument for making technology the enemy. Online banking, investing tools, and digital commerce are part of adult life. The goal is to give children enough real-world practice that they are not easily pulled along by every prompt, sale, influencer, or limited-time offer.
Money education also strengthens all four dimensions of healthy development. It builds thinking skills when children compare choices, emotional skills when they tolerate disappointment, social skills when they consider generosity, and practical life skills when they plan ahead. A child who learns to say, “I want this, but I am going to wait,” is building more than a budget. They are building self-direction.
Children do not need the same lesson at every stage. Start with the next skill your child can reasonably practice, then let repetition do the teaching.
Young children learn through what they can touch and see. Let them hand cash to a cashier, place coins in a clear jar, or help sort coins by size. The lesson is simple: money is used to get things, and when it is spent, it is gone.
Use short, concrete language. Say, “We are choosing apples today, so we are not buying candy,” rather than giving a long explanation about the household budget. At this age, the real win is helping children understand that choices have limits.
If they see you pay with a phone, explain the action. “My phone is how I pay, but the money still comes from our bank account.” That one sentence helps prevent the common belief that screens create endless money.
This is a strong age for a modest allowance or earned money system. Families differ on whether chores should always be paid, and either approach can work. Some parents give a regular allowance to practice managing money while expecting basic household contributions as part of family life. Others pay for selected extra jobs. What matters is consistency and clear expectations.
Give your child a chance to divide money among spending, saving, and giving. Three labeled jars or envelopes work well because the system is visible. Do not rush to correct every choice. If they spend all their fun money on a toy that loses its appeal by dinner, that disappointment is a useful lesson when the stakes are small.
When requests arise at the store, avoid turning every “no” into a lecture. Try: “That is not in today’s plan. You can save your spending money for it, or put it on your wish list.” This teaches a child that wanting something is normal. Getting everything immediately is not.
Preteens can begin to understand that money has jobs. They can compare prices, calculate how long it will take to save, and notice the difference between a need, a want, and a marketing message designed to create urgency.
Include them in small family decisions. Ask them to compare two brands at the grocery store or help plan the cost of a movie night. Let them see that a lower price is not always the best value, especially when quality, quantity, or usefulness differs.
This is also the right time to discuss digital spending directly. Review how game currencies work. Explain that a $10 gift card can disappear through several small purchases, even when each purchase seems tiny. If your child plays games with purchases, set a family rule that no money is spent online without a pause and a parent conversation.
The pause matters. It creates space between impulse and action, which is one of the most valuable money skills a child can develop.
Teenagers need increasing freedom with a clear safety net. Give them responsibility for a category that fits your budget, such as clothing, entertainment, gifts, or part of a phone bill. Then help them plan for it monthly rather than rescuing every poor decision.
Talk openly about larger realities: taxes, debit cards, credit, subscriptions, borrowing, and the cost of convenience. A teen should know that a debit card spends money already available, while a credit card creates a bill that must be paid. They should also understand that a free trial can become a recurring charge and that buy-now-pay-later offers are still debt.
If your teen earns money, encourage them to save a portion before spending. The exact percentage depends on your family and their goals. A teen saving for a car, college, or a future move needs a different plan than one earning occasional babysitting money. The principle is more important than the formula: pay your future self first.
The most effective money conversations often sound like curiosity, not correction. When your child wants something, ask, “What do you like about it?” and “What would you give up to get it?” When they see an online ad, ask, “What is this company hoping you feel right now?”
These questions develop judgment. They help children identify the pull of scarcity language, social pressure, and influencer culture without shaming them for wanting what their friends have.
At the same time, let your child see your values in action. You do not need to reveal every financial detail, especially when money is tight. But you can say, “We are saving for something important,” “We compare prices before we buy,” or “We chose to repair this instead of replacing it.” Children learn from the patterns they witness repeatedly.
A family rule that says “ask before buying” is a start, but it is not enough if devices hold saved payment information and purchasing is frictionless. Remove stored cards from children’s devices where possible. Use parental controls and purchase approvals. Review subscriptions together, especially for older children with their own accounts.
More importantly, connect screen boundaries to the bigger lesson. The issue is not simply that games or apps cost money. The issue is that companies benefit when people make fast, emotional decisions. Your child needs practice noticing the feeling behind the click: boredom, excitement, fear of missing out, or the hope of fitting in.
That awareness changes everything. A child who recognizes, “I want this because everyone else has it,” has a chance to make a different choice.
Parents naturally want to protect children from regret. Yet constantly replacing lost money, covering overspending, or buying the item they could not wait for teaches the wrong lesson: consequences disappear when feelings are uncomfortable.
Be compassionate without taking over. You might say, “I know you are disappointed. You worked hard for that money. What will you do differently next time?” Then help them make a realistic plan. A child who loses $15 now and learns to track it may avoid far more expensive mistakes later.
Money confidence is not built by raising children who never want anything. It is built by raising children who can want, wait, choose, recover, and keep moving toward what matters most. Start with one ordinary family decision this week, give your child a real role in it, and let that small practice become part of the person they are learning to be.

There are no comments